
 Posts


Monday, December 25, 2006


Thursday, December 21, 2006
November Recap…
Looking back at November, I don’t feel so bad. December will be another story with Christmas. Driving the decline in my net worth for November was the depreciation of my car and the interest capitalization on my student loans. I still spent too much on discretionary purchases to the tune of $1500, which was mostly eating out again. Overall, I don’t feel too bad but I am looking forward to my net worth improving in the near future.
I expect my net worth to decline for the next three months and then hopefully improve from then on out. For December, I have Christmas purchases, my tuition bill is due in January and I have bar exam fees due in February. I finish law school in May. My federal loans go into repayment six months later in December 2007 and my private loans go into repayment nine months later in February 2008. Oh joy!!!
Still no luck finding a job for next year but I am looking all the time and trying to meet with people to network.

Wednesday, December 13, 2006
Dodged a Shopping Bullet…
What did I do?
Shopped for everything I wanted and then closed the link before I purchased anything. Then I sent my mom and e-mail and told her to check out my shopping basked at JCrew for more Wish List ideas…
She is going to crack up laughing and do what???? Close the link too. LOL
Be a Millionaire...
CNNMoney.com has a article today called Be a Millionaire: 5 Ways to Get There.
The 5 ways highlighted in the article include the following:
- Make Saving Automatic
- Take Advantage of Uncle Sam
- Make Stocks Work for You
- Boost You Earning Power
- Don’t Stop Saving
Enjoy!
Monday, December 04, 2006
Blogging Vacation...
I got a rejection e-mail from one of the firms I interviewed with in October. All of their Summer Associates accepted their offers and therefore the firm satisfied their hiring needs for next year. Bummer!!! I haven’t heard back from one other firm so I sent my interviewer an e-mail for a recruiting status update this morning. I will post the results from that e-mail as well.
My 29th Birthday was great. I had a lot of fun over the weekend. My grandmother celebrated her 84th Birthday on Sunday so I have a lot to be thankful for.
Cheers!!!
Thursday, November 30, 2006
Gift Card Warning...
Here is an article from CNNMoney.com that warns about buying gift cards. Holiday shoppers click here.
Time for Final Exams…
I registered for my LAST AND FINAL SEMESTER of law school and I am gearing up to finish strong. No job offers yet but the operative word is YET! Something will come my way. Something good!
My 29th Birthday is on Saturday!!!
Wednesday, November 29, 2006
6 Ways to Cut Heating Bills…
In the meantime, CNNMoney.com has an article that details 6 ways to cut your heating bill. I know that changing over from a manual thermostat to a programmable thermostat has already reduced my electric bill considerably.
Check it out here.
Thursday, November 16, 2006
401k Contribution…
I decided to change my 401k contribution rate from 5% to 10%. This will amount to approximately $675 contributed each month. Although my employer only matches 5%, I know it is a good move in the right direction towards establishing a continuous pattern of saving. I was going to wait until next year but I can’t come up with a good answer for why I should put it off when I am blowing through cash and don’t have sufficient income at the moment for debt repayment.
Why change to 10% when I have so much debt?
It’s easy. I am simply out of control and living way beyond my means. I know that I won’t touch my retirement account so it is safe and out of harms (MY) way. Right now, it is the only method of savings that I have. I am going through the savings in my checking account left and right now with irregular and unexpected expenses popping up everywhere.
- Car Insurance Deductible = $250
- Passport = $100
- Sister's Destination Wedding = $1,600
- License Plate Renewal = $100
- Christmas = $1,000 Budget (just being realistic about this one – saved in ING account for Christmas)
It just makes sense to me to make sure I am doing something right. In my bleak state, here are some good things.
- Everything is paid on time.
- $50k in equity in my condo.
- I have been a homeowner since age 25.
- Graduate from law school in May 2007 – just 6 more months.
- Flexible repayment for student loans.
- Private loans don’t go into repayment until February 2008.
- Car is paid off and I am content with driving it for many more years.
- I am able-bodied to get a second job if necessary once law school is over.
- I have great employment credentials.
- I have the love and support of my family.
In the grand scheme of things, I am doing all right. Things will get better. I just need to stay focused on the big picture.
Wednesday, November 08, 2006
Lacking Motivation…
I am sincerely lacking motivation these days and yet, I have so much on my plate it’s crazy.
Here is a brief list…
- Working full-time
- School part-time – 4 nights a week
- Car accident – neck still hurts a little
- Mom recovering from knee surgery
- Sister getting married
- I have strep throat but feel much better
- Having a hard time trying to find a law job after graduation
- Student loan debt is piling high
- 25-page paper due in a month
- Class presentation in 2 weeks
- Final exams start in a month
Need I go on? I keep telling myself that I only have until May and then I graduate but any law student knows that graduation is when the REAL work starts. LOL Needless to say, I am at least looking forward to finals being over and getting a chance to relax.
Like most PF bloggers out there who may dread the purchase of Christmas gifts, I am looking forward to just spending some quality time with my family. Fortunately, with my upcoming graduation, my sisters nuptials, my mother’s retirement from teaching after 35 years, and my 30th Birthday (shhhhhh!!!!!), we are keeping gifts light and going heavy on having a good time with each other.
Tuesday, October 31, 2006
October 2006 Recap…
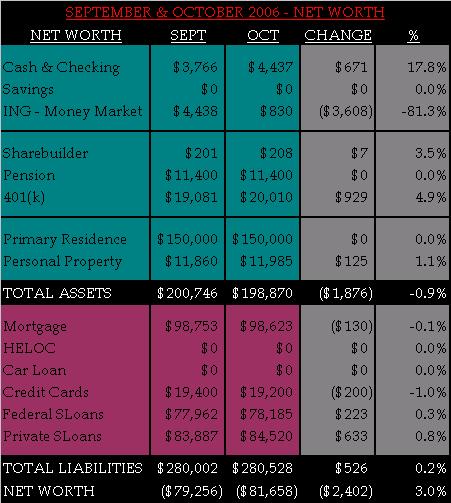
I am beginning to loathe these recaps but only because of MY bad financial behavior. I can deal with large expenses like tuition payments, new tires for my car or something like that but it’s my discretionary spending that is out of control. It is this blog that lets me know just how much!!!
Okay, here goes…
Snapshot:
- Blew through cash reserves
- 401k rocked this month
- Car value holding steady
- Still trying to deposit $100/month into savings
- Student loan interest is killing me
- Probably need to revalue my condo - neighbor sold 2bd/2ba for $155, I have a 3bd/2ba
- Opened WaMu high interest bearing online savings account – 5% current APR
- Withdrew ShareBuilder bonuses and transferred to ING – Moving ING funds to WaMu on November
Major Expenses:
- Quarterly Water Bill - $110
- Bar/Bri Prep Program - $170
- Car Tires and Brake Repair - $870
Next Month:
- Watch discretionary spending closely
- Move $2-3K into WaMu savings account – waiting for checks and debit card
- Pay for my trip to my sister’s wedding – need to get this secured and out of the way
- Pay for passport
- Pay $250 deductible for car repair

Monday, October 23, 2006
Neighbor Sold Condo…
I have a 3 bedroom, 2 bath that I purchased for $129k almost 3.5 years ago and he purchased 6 months after me. I currently value my condo at $150k so I think that after I sell my place, I can definitely net at least $50k in equity since my mortgage balance is down to $98.6k and I don’t plan to move for another 3 years. This money can go towards a new home purchase or the pay down of my student loans. Oh yeah!!!
New WaMu Account…
Working downtown in Chicago, there are a lot of WaMu braches and there are several that are near my home outside of the city. Like all other online savings account, the APY is subject to change but the account is fee free and I am able to access my funds a lot easier because there are so many braches nearby. I am going to probably switch to using this rather than HSBC but I will see how I like the account first.
Some other benefits…
The WaMu Free Checking account has:
- No minimum balance or direct deposit requirements
- Open with $1- Free basic checks for life
- No ATM fees on their end
- Free Gold Debit MasterCard® with Rewards—earn cash back on purchases!
- One free overdraft per year- Free outgoing wire transfers
The Statement Savings account has:
- A competitive 5.00% APY on all balances (rate only available online)
- No minimum balance requirements
- Open with $1- Instant transfer to/from the Free Checking
Thursday, October 19, 2006
When it Rains, it Pours…
So, all in all, I will have to pay my insurance deductible to get the work started on my car and get a rental but my car is drivable…just embarrassingly damaged. Besides, I don’t really blame the woman too much because she just moved here from the South and is unfamiliar with how fast Chicago moves and the sheer amount of one-way streets in Downtown Chicago. If you are new here, it can be very difficult.
The most important thing is that nobody got hurt. The car can be fixed but people are not replaceable and I am grateful that it wasn’t worse.
Tuesday, October 17, 2006
Waiting Period for Purchases…
So here goes…I am going to try a 30-day waiting period. Hopefully, I will be able to increase this to 60 days and eventually 90 days. In the end, I can try to save for whatever it is that I want during this waiting period.
I mulled the purchase of my new PDA/Cell phone for about 6 months before I purchased it and I am very happy with it. But by waiting the whole 90 days, I could have easily set aside $100/ month for the purchase and it wouldn’t have hit my pockets so hard. Plus, you never know if the urge to buy whatever will go away, if you will find something else that’s cheaper or if the item will go on sale.
Thanks Tricia!!!
Monday, October 16, 2006
October Update…
Monthly Income: $3,130 – After 5% 401k contribution
Savings: $300
Regular Bills/Expenses: $2,250
Discretionary Spending: $915
Irregular Expenses: $1,150
- Quarterly Water Bill - $110
- Bar/Bri Prep Program - $170
- Car Tires and Brake Repair - $870
Deficit: $1,485
Tuesday, October 10, 2006
September Recap...
Irregular Expenses: ~ $1,300 (OUCH!!!). I don’t have to tell you that this completely threw my budget out the window. Luckily, I got $900 extra in September in tuition reimbursement that helped out a lot.
Interview Expenses: $330
Law School MPRE Exam: $60
Car Repairs: $260
New PDA/Cell Phone: $380 - $100 Mail in Rebate so $280
New Computer Battery: $80
Garage Door Repair: $100
Birthday Gifts: $100
Discretionary Spending: ~ $1200. Once again, I spent way too much but I know it would have been worse using my CC. Not so much on clothing or anything like that, just eating out and entertainment spending. This spending would be in line with a salary in the $135k range, not my $54k salary.
Savings: I transferred $4,000 of my Savings into ING and have since transferred the funds back to my checking account. MY HSBC account is now up, running, and set to go and I just need to call and have them fax me the beneficiary form so I can fill it out and fax it back. Then I will transfer the $4K back and out of “harms way.”
Investments: I invested another $100 with Sharebuilder and that account is building nicely. We have to start somewhere right? In October, I deposited another $100 and should get the $50 and $25 bonuses in the coming weeks to add to my accounts as well.
Retirement: My 401k performed much better and almost doubled my contributions for the month. Oh yeah! My friend is a financial advisor so he did a new asset allocation for me and it is working out well.
Debt: Student loan interest continues to stack up and capitalize. I am grateful that this is my last year of law school so I can start paying some of this debt off soon.
General comments: Overall, a slight dip in net worth but nothing like last month. It will suffer another dip in January with my last tuition bill but from there on, it should be smooth sailing to financial freedom. I am still interviewing and have another interview this week. I am waiting to hear back from 2 firms that I interviewed with in September. Both are long shots but I am just as deserving as the next, hungry for the opportunity, and know that I can do a great job for whoever hires me. What is meant to be will be, I just have to continue to put my best foot forward.

Thursday, September 21, 2006
September Update…
September is moving right along. I am pleased to say that I’m loving the cash only system. It is absolutely wonderful. I will also say that I am less anal as well with balancing everything. While this may be a bad thing for some people, I think that it is working well for me because I was becoming obsessed with writing down every dime that I spent. I was spending so much anyway that 1) it didn’t help and 2) I never had time to go over my spreadsheets. So I use the Bank of America Keep the Change Checking account and use it solely for my personal spending. I am able to track it that way. I use my other bank account for unexpected expenses like my car repairs this month.
Car Repairs…
Speaking of car repairs, I just spent $260 to get my car serviced, including cooling and transmission flushing, oil change, tire rotation and winterizing. Right now, my car is 4 years old and has 45k miles on it. I drive about 100 miles a day, 4 days a week downtown to work. The dealership serviceman also told me that I would need 4 new tires before winter because they were near bald. This is scary business especially considering the sheer amount of driving that I do daily. So, I am going to do my research and try to find a good deal on the tires and have them replaced soon. Winter here in Chicago is approaching quickly.
Employment…
As many of you know, I had 2 call back interviews and I am in wait and see mode. I also haven’t heard back from another firm and sent them a follow-up letter that still expressed my interest. I would love to work for either firm and would be blessed to get an offer. I am still doing my best to network, network, network but it is extremely hard with my schedule and completely wrong and difficult to make personal calls from work regarding employment at another company. So, I am forced to make many of my calls from home on Fridays since I need a new cell phone and the only one have now is cheap and completely unreliable. Yet another expense that I will incur soon. I am going to bite the bullet and get one with a PDA because I need a way to keep up with my crazy life.
Savings/Investment Update…
Right now, I have approximately $4,400 in my ING accounts. Once my funds become available, I am looking to move my long-term savings of $4k to Emigrant since they have a beneficiary designation form. I will keep my short-term savings with ING and continue to fund it with $100 automatic investments every month. This account is for my sister’s wedding next year.
I opened another ShareBuilder account to get a $25 bonus. I am hoping to be able to invest $200/month into ShareBuilder. I chose SPY, which is the S&P 500 Index.
That’s it for now. Thanks for reading this long post. LOL!!!
Friday, September 15, 2006
Major ING Drawback...
So over the last 2 days, I’ve been thinking about the fact that I never signed a beneficiary form for my accounts...like I do with a traditional bank account. So, if something were to happen to me, the funds can go directly to that person. Since I’m not married and don’t have any children, my parents are the beneficiaries of my bank accounts, insurance, and retirement funds. Although I don’t have a trust established or a will (I will need to do this soon!!!), I know that they will receive everything because they are named beneficiaries using will substitutes. My condo is another issue.
I don’t share all of my financial business with my family so it’s not like they would know I have online savings accounts. The only other option that I have is to make the account a joint account and I don’t want to do that either.
Yes...I am leaning towards pulling my money soon. This is one I can’t get comfortable with especially since you never know what may happen in today’s day and age.
Wednesday, September 13, 2006
September Progress Report…
I am plowing my way through September. I had some job seeking related expenses like parking for interviews, new interview shoes (my other shoes hurt like hell), and some dry cleaning expenses. I know I need to curb my eating out expense but I don’t have the focus or energy right now with work, school, interviewing, etc. That’s enough right! LOL
Anyway…I am still waiting for a $900 tuition reimbursement check. I opened a new ING account and deposited $4k of my savings. I will deposit additional funds at the end of the month because I still have about $4k sitting in my checking account and I want to have that number around $2k.
Can anyone tell be about their experience with HSBC? They have a better savings rate than ING so I may look to transfer my long-term savings/ debt repayment funds into that account.
So far, I have approximately $45 in my Bank of America Savings account from the automatic $25 monthly checking transfer and regular Keep the Change deposits from my checking account debit transactions. I will be transferring the balance of that account to my ING account at the end of the month.
Thanks a bunch!!!